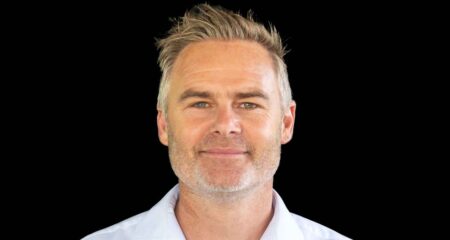
Ferdi Moolman has worked for MTN for most of his career, but until he took over as CEO of its South African business late last year, almost none of that work was done in South Africa. He left the country at the turn of the century, ran MTN Nigeria until 2021 and returned to the group as chief risk officer before taking the South African job.
He is frank about what that distance does to an executive’s instincts. “When you’re out of the country that long, it doesn’t matter how many times you come back – you lose track of what’s happening,” he told TechCentral in an interview last week. Anyone returning after that long and assuming they still understand the country, he said, is starting on the wrong foot.
He includes himself in a wider misjudgement. Moolman sat on the MTN South Africa board as a non-executive director from 2021, and says that from that seat the business looked straightforward. “I used to look at [my predecessor] and think these things are easy, man. Just do this, just do that – until it’s you, the proverbial dog that catches the car.”
The danger, he said, is that MTN executives coming from other markets speak the same language and assume the mechanics are the same. In South Africa they are not, and the differences are to be found in almost every part of the operation.
For example, MTN barely touches the handset business outside South Africa. The reason is the grey market: in most of its other territories, the landed cost of a handset sold through the operator puts it out of reach against grey imports, so consumers never developed the habit of choosing a network on the strength of a device deal.
In South Africa they did, and Moolman said the consequences of this go well beyond top-line revenue into how bundles and packages are structured and how churn is managed.
How the business carries risk
The prepaid/post-paid split is just as different. In MTN’s other operations, prepaid accounts for more than 90% of revenue. In South Africa it is closer to half. That changes how the business carries risk, he said, because a mature post-paid base means a materially larger bad-debt exposure than the group is used to elsewhere.
Even within post-paid, MTN’s book does not look like Vodacom’s. Moolman traces that to the start of the market: Telkom was still a fixed-line business and Vodacom’s main shareholder, so affluent households with landlines moved naturally to Vodacom, while MTN built more of a prepaid play. MTN has a post-paid book, he said, but the profile is different.
Another sharp contrast is in how money reaches MTN. In Nigeria, most recharge cash comes through bank channels – a subscriber opens a banking app and buys airtime directly. MTN deals with the banks directly, and where intermediaries exist they are technical rather than commercial, providing the connection rather than holding the cash. Money from a recharge at the country’s largest bank is in MTN’s account the next morning, Moolman said, if not immediately.
South African intermediaries are both technical and financial. “If you recharge and there is an intermediary in place, I could wait up to 60 days or 90 days for that cash to hit my bank account, because it goes from the bank to the intermediary and then it comes to us,” he said.
That is the context for a remark he made at a recent MTN Group media day: he cannot see why a multinational operator does not have a direct relationship with the banks. He is careful to say this is not a move against Blu Label, which he calls extremely important to MTN, but he acknowledges the sensitivity. “If I start speaking to a Capitec directly, then Blu Label gets upset.” When MTN approaches a bank, he said, it has to be conscious of the relationships it might damage elsewhere.
He argues Blu Label’s model was evolving anyway. The company began in prepaid electricity before mobile overtook it, and its newer universal voucher – redeemable across airtime, electricity and other services – functions as a form of cash. The significance, in his view, is that it moves the decision away from the shop counter. A consumer who previously had to choose at the point of purchase how much of the money in their hand went to electricity and how much to airtime can now buy one voucher and decide at home, spending as they go.
That, he said, is why intermediaries remain part of the value chain even as MTN moves closer to its own customers: unlocking the cash economy in townships is work MTN cannot claim to do better itself. “If we claim to understand the entire retail market, we would be making a mistake.”
Mature in wholesale
The one area where South Africa is ahead of the rest of the group is wholesale, which Moolman describes as a different business from consumer telecoms rather than an extension of it. Nigeria is only now moving into it, partly through arrangements with mobile virtual network operators and partly through an arrangement with a new entrant that resembles MTN South Africa’s deal with Cell C, in which spectrum forms part of the exchange.
Enterprise is also more advanced in South Africa than in MTN’s other markets, but behind its local rivals. Telkom has BCX, which has had its problems but is more mature than anything MTN has built, and Vodacom draws on Vodafone’s developed-market enterprise model. – © 2026 NewsCentral Media