Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Vodacom targets satellite-to-phone service in South Africa next year

      Vodacom targets satellite-to-phone service in South Africa next year

      10 November 2026
      Vodacom eyes SA and Kenya for AI data centre hubs after Egypt - Shameel Joosub

      Vodacom eyes SA and Kenya for AI data centre hubs after Egypt

      10 November 2026
      Eskom chairman Mteto Nyati and energy minister Kgosientsho Ramokgopa speak to the media in Irene, Pretoria

      South Africa’s first new nuclear reactors could be online by 2036

      10 November 2026
      Comsol's 5G network pricing comes into view

      Comsol’s 5G network pricing comes into view

      10 November 2026
      Safaricom ruling tripped default clauses in Vodacom's loans

      Safaricom ruling tripped default clauses in Vodacom’s loans

      10 November 2026
    • World
      John Ternus faces first big test as Apple CEO - John Ternus

      John Ternus faces first big test as Apple CEO

      2 November 2026
      Alleged Israeli spy company heavily targeted Starlink users

      How online ads were used to hunt Starlink users

      28 October 2026
      Anthropic's IPO stands alone

      Anthropic’s IPO stands alone

      23 October 2026
      PHP flaws trigger global scramble as hackers pounce

      PHP flaws trigger global scramble as hackers pounce

      22 October 2026
      OpenAI turns the tables on Apple in trade secrets fight

      OpenAI turns the tables on Apple in trade secrets fight

      15 October 2026
    • In-depth
      Ducking hell: inside Apple's hidden list of words the iPhone won't suggest

      Ducking hell: inside Apple’s hidden list of words the iPhone won’t suggest

      6 November 2026
      Why investors are souring on Netflix

      Why investors are souring on Netflix

      22 October 2026

      10 days that changed the course of AI

      21 September 2026
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
    • TCS
      TCS+ | Old Mutual's Celiwe Ross on leading people through AI - Old Mutual

      TCS+ | Old Mutual’s Celiwe Ross on leading people through AI

      6 November 2026
      TCS+ | How the Apple ecosystem drives productivity for SMEs - Sudesh Pillay iStore and Kevin McLennan

      TCS+ | How the Apple ecosystem drives productivity for SMEs

      6 November 2026
      TCS+ | Vox on AI, data rules and omnichannel communication for SMEs

      TCS+ | Vox on AI, data rules and omnichannel communication for SMEs

      26 October 2026
      TCS | The Cape Town firm quietly connecting Eskom, Pep and 6 000 ATMs - Rรฉan van Niekerk, Metacom

      TCS | The Cape Town firm quietly connecting Eskom, Pep and 6 000 ATMs

      23 October 2026
      TCS+ | Boards are underestimating the cost of a cyberattack, says Arctic Wolf - Jason Oehley and Andre Den Hond

      TCS+ | Boards are underestimating the cost of a cyberattack, says Arctic Wolf

      22 October 2026
    • Opinion
      Icasa's Sim rules need a privacy backstop - Lloyd Matthew and Heinz Vollmer

      Icasa’s Sim rules need a privacy backstop

      5 November 2026
      AI's boardroom honeymoon is over - Gary Stocks

      AI’s boardroom honeymoon is over

      22 October 2026
      Before South Africa licenses Starlink, it should look at Ukraine - Duncan McLeod

      Before South Africa licenses Starlink, it should look at Ukraine

      21 October 2026
      Nonkqubela Thathakahle Jordan-Dyani

      Why cybersecurity is now a national security issue for South Africa

      15 October 2026
      When a machine can choose, who does it become? Fanie van Rooyen

      When a machine can choose, who does it become?

      9 October 2026
    • Company News
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Publishared
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Fintech and payments
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home ยป Sections ยป Cryptocurrencies ยป The road to regulated blockchains in South Africa

    The road to regulated blockchains in South Africa

    Given money on blockchains, other assets, and the rest of the financial industry, will soon follow.
    By Paul Mitchell7 June 2023
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

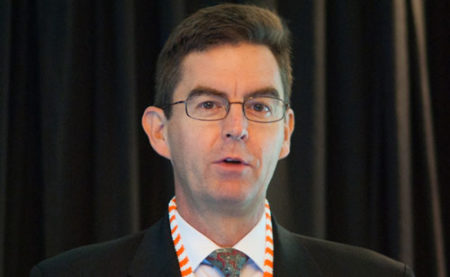
    The author, Paul Mitchell

    Money on blockchains is inevitable. The component pieces are the regulations, the technology and the behaviour. The regulations and the technology are pretty clear; the behaviour comes down to wants and needs. Looking at these push and pull factors suggests how we will see regulated blockchains emerge โ€“ organically, driven by builders creating valuable products for real people.

    Starting point

    From where we are now, midway through the second quarter of 2023, that we will soon have money on blockchains looks inevitable. Many would argue that we are already there, given that bitcoin launched in 2009, or given the US$130-billion in stablecoins on public blockchains. The specific case that we are considering here, though, is the regulated version. What this probably means is some form of money issued by regulated institutions using blockchains as the underlying technology. When we have this, we will have blockchain based payments, and therefore the basis of a decentralised financial markets infrastructure (DFMI). But how do we get there?

    Regulations, technology and behaviour

    To use strategist Roger Martinโ€™s test: what needs to be true for this to be a great idea? I think there are three pieces we need to get straight: regulation, technology and behaviour. The regulatory question is becoming clear. We have stablecoin regulations defined in many countries, not least in the European Union with the MiCA regulations recently approved by the EU parliament, but in many other progressive jurisdictions, too.

    Many of these rules donโ€™t come into law for several months, but the frameworks have been defined to allow financial institutions and others to put the right structures in place in advance. Broadly, these regulations treat stablecoins backed by fiat currency in a similar way to e-money. This means that the token is treated as a liability of its issuer. In legal terms, this is the same as other forms of money: cash is the liability of the central bank, and my bank balance is the liability of my retail bank. E-money is the liability of the licence holder.

    The technology behind stablecoins is now well understood by a growing population of specialists

    The technology behind stablecoins is now well understood by a growing population of specialists. Blockchains and wallets that connect to them have been in play since bitcoin launched 14 years ago. The wallet controls the cryptographic passwords that enable the owner to prove their identity and thus control their assets. In this sense, the concept is very similar to a bank account, where knowing my account number and passwords will get me access to my money. That bank account may be managed by the bank using any system, be it Temenos, Finastra, FlexCube,or whatever, but as a user I donโ€™t care. The same will be true of blockchain based money: the blockchain is just the technology in the background.

    Behaviour is the core of the challenge

    The tricky one is behaviour. Iโ€™ve chosen this term because it is about what people and institutions (which consist of people) will actually do. As the saying goes, itโ€™s easier to get someone to open their mouth than to open their wallet. There is a lower barrier to forming an opinion than to forming an intent.

    To get to a point where money on blockchains is a normal form of financial market infrastructure, we need to have blockchain based financial products, and we need people to use them. These two are necessary and in combination with the technology and regulations mentioned above, they are sufficient. But what makes people and institutions actually do things?

    I think there are two things: wants and needs. The things you want to do, and the things you have to do. I want my ice cream; I have to eat my broccoli. I want to be fit; I have to train. I want to make payments simple; I have to implement 2FA. It works the other way too: I have to get to work; I want a BMW. I have to have somewhere to live; I want a mortgage to buy a house.
    This push and pull is behind the history of any change, and the progress towards regulated blockchains will be no different. To understand how we get to a world of blockchain or web3 based finance, it helps to view it through this lens. If we look at the adoption of this technology, we can see both forces at play.

    At the edge cases, where crypto has taken hold, we see the first real adoption of blockchains. There are two big use cases so far. One is, bluntly, gambling: speculation on cryptocurrencies and trading of these volatile new assets. This is driven by desires (mainly greed), pulling people to use this technology. The other thriving use of crypto is where there is a real need for it, because the alternative is not working. Thus we see adoption of crypto by โ€œreal peopleโ€: tens of millions of people in Africa buying US dollar based stablecoins. South Americans use Tether to transact every day. At a national level, we have seen El Salvadorโ€™s experiment with bitcoin as legal tender: despised and discouraged by the IMF, but leading to more bitcoin wallets than bank accounts within a few weeks of launch.

    Behavioural forces in traditional finance

    In the world of traditional finance, the push and the pull are both working. For commercial banks and central banks, the push takes the form of being compelled to investigate blockchain based infrastructure by external forces. The pull comes from a desire to explore new ideas. Put another way, the pull is from a desire to innovate, while the push is from a need to innovate.

    Thus we see central banks needing to respond to the threats of crypto and global stablecoins like Libra/Diem. At the same time, they want to explore the new tools that CBDC could provide in terms of monetary policy: things like purpose-bound money. Commercial banks need to remain relevant as their corporate and retail customers embrace web3 and demand new solutions, and they want to seize the opportunity to build a base of programmable money on which they and their clients can innovate.

    If we look at what has happened in South Africa so far, we have seen the SA Reserve Bankโ€™s wholesale central bank digital currency (CBDC) experiments: project Khokha and Khokha 2. There has been other work at the SARB, including on retail CBDC, and at the same time, most of the commercial banks and other large institutions have been building blockchain based proofs of concept.

    None of this other work is yet public. Looking forward from the end of PK2, we are awaiting a paper from the SARB on stablecoins, which should provide guidance on the regulatorโ€™s approach. It would be a surprise if it was not aligned with global guidance and emerging best practice for legislation.

    Potential launches of regulated money on a blockchain

    In this context, there are three potential sources of blockchain based money. The technology has been widely tested, the regulations are clear, and so the key question is the behavioural one: what will drive the adoption? The driving force โ€“ want or need โ€“ should be considered in terms of the potential candidates for launching regulated money on blockchains. There are three potential candidates: the SARB, commercial banks, or a fintech.

    The SARBโ€™s version of tokenised money would, of course, be CBDC. They have already indicated that there are no short term plans to launch a CBDC in SA. A wholesale one would be more likely than a retail CBDC, as it would require less adjustment to the current banking system. It could replace the RTGS system, Samos, as tested in Project Khokha, and it could then act as the settlement asset for an interbank stablecoin.

    The Samos system facilitates the settlement of domestic individual high-value payment transactions, retail transaction batches, and bond and equity market settlement obligations. This is speculation at this stage, though, and this scenario has to be considered unlikely for the near future. The pull for the SARB to issue CBDC is, at this point, too weak. The push might come if and when CBDCs globally become more common, and then South Africa might be putting itself at a disadvantage by not having one. CBDCs enable currencies to compete on features as well as economic fundamentals, which might be something that South Africa cannot afford to pass on.
    For a commercial bank stablecoin, there are two options. One is for the banks to cooperate and agree on the mechanism for things like collateral transfer backing up transactions, enabling them to launch a multi-issuer coin. Given the different stages that banks are at, particularly if we look at the smaller banks, this is also unlikely. More likely is that a single bank recognises the value of building a stablecoin ecosystem around their own coin, issued for their customers.

    This is what JP Morgan has done through their Onyx team with JPM Coin. The coin is used for moving value around JP Morgan and its clients across its global network, and has also given the Onyx team the skills to offer a wider range of blockchain and tokenisation services. A large African bank, ie, one of SAโ€™s big four, could get significant benefit from their own version of this approach. There is therefore a clear pull towards a single bank issuing a stablecoin. If they did, then there would be a push factor for other banks to join the scheme.

    The final route for getting tokenised money released into the wild is firmly driven by a want

    The final route for getting tokenised money released into the wild is firmly driven by a want. As we have seen in crypto, retail customers will use products to solve problems that cannot be solved any other way. The most likely route for a stablecoin is therefore its launch by an entrepreneurial fintech to enable tokenised financial services.

    By building products that draw customers in, it will be possible to create an ecosystem to serve a growing group. This will attract more customers, more service providers, therefore more customers, and so on. At this stage, traditional FS businesses will feel the push to participate, and we are off and running.

    New DFMI systems can satisfy both the wants and needs of a large customer base, especially in emerging markets. As we might have guessed up front, innovative small companies are best placed to start this revolution. The big thing to note is that it can all be done within the current regulatory frameworks.

    Given money on blockchains, other assets, and the rest of the financial industry, will soon follow. This first piece of the new financial infrastructure is what we are building at Block Markets Africa.

    • Paul Mitchell is adviser at Block Markets Africa

    Get TechCentralโ€™s daily newsletter

    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    Block Markets Africa Paul Mitchell
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleHistory suggests bitcoin is poised for a big rally
    Next Article Andy Openshaw steps down as director of Huge Group

    Related Posts

    ‘Sensing networks’ could ease spectrum scarcity

    4 October 2011
    Company News
    The hidden risks of fragmented IT and unenforced SLAs - ITC Systems Durban

    The hidden risks of fragmented IT and unenforced SLAs

    10 November 2026
    Why AI-powered customer experience will decide South Africa's festive retail winners - CM.com

    Why AI-powered customer experience will decide South Africa’s festive retail winners

    10 November 2026
    Traditional QA undermines modern customer experience - Martie de Beer, Telviva

    Traditional QA undermines modern customer experience

    10 November 2026
    Opinion
    Icasa's Sim rules need a privacy backstop - Lloyd Matthew and Heinz Vollmer

    Icasa’s Sim rules need a privacy backstop

    5 November 2026
    AI's boardroom honeymoon is over - Gary Stocks

    AI’s boardroom honeymoon is over

    22 October 2026
    Before South Africa licenses Starlink, it should look at Ukraine - Duncan McLeod

    Before South Africa licenses Starlink, it should look at Ukraine

    21 October 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    The hidden risks of fragmented IT and unenforced SLAs - ITC Systems Durban

    The hidden risks of fragmented IT and unenforced SLAs

    10 November 2026
    Why AI-powered customer experience will decide South Africa's festive retail winners - CM.com

    Why AI-powered customer experience will decide South Africa’s festive retail winners

    10 November 2026
    Vodacom targets satellite-to-phone service in South Africa next year

    Vodacom targets satellite-to-phone service in South Africa next year

    10 November 2026
    Vodacom eyes SA and Kenya for AI data centre hubs after Egypt - Shameel Joosub

    Vodacom eyes SA and Kenya for AI data centre hubs after Egypt

    10 November 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter