Adopting AI has proved considerably easier than turning it into measurable enterprise value. McKinsey’s 2026 State of AI survey found that 80% of respondents believe AI has improved their individual productivity, but only 37% report any impact from AI on earnings before interest and tax.
Organisations have moved quickly to deploy copilots, chatbots and other AI tools, but individual productivity gains are not consistently translating into financial returns for the enterprise. As Harvard Business Review has noted, AI can save employees time without improving the bottom line, particularly where people must still review outputs, manage exceptions and manually integrate AI into existing processes. McKinsey’s research suggests more value is achieved where companies redesign business processes end to end, rather than simply adding AI to existing ways of working.
We are seeing this in practice at the JSE. Generic productivity tools are available across the organisation and are materially improving the productivity and quality of specific tasks. We are also using AI in the modernisation of one of our core exchange systems, where it is helping to analyse complex legacy code, derive business requirements and generate test cases. In another initiative, we are exploring how AI can extract and interpret information from public sources and announcements more efficiently.
The challenge is translating these gains into sustained improvements in business performance.
Our recent JSE Future Competitiveness Forum provided useful evidence of where value is beginning to emerge. One large South African financial services group reported that around half of the servicing interactions in one of its businesses had shifted from voice to AI within three months, and that AI had contributed to a 95% reduction in client fraud losses in certain areas. A technology investor cited about US$100-million in AI-related cost savings at one of its portfolio companies. What struck me was that these measures went beyond adoption and tied AI directly to customer experience, risk reduction and financial outcomes.
Applying discipline to AI investment
One question raised at the forum was: when everyone has AI, what becomes the competitive advantage? As AI becomes more accessible, the advantage is more likely to lie in how effectively companies apply it, and whether they are prepared to change established ways of working to realise the benefits.
That requires greater discipline around investment. Boston Consulting Group (BCG) has estimated that corporate AI spending has more than tripled in two years to 3.3% of revenue, and that 80% of it now sits outside enterprise IT budgets. As the sums grow, AI is becoming less a technology budget decision and more a question of capital allocation.
It should compete for capital on the same basis as other strategic investments. Boards and management teams need to be clear about the intended outcome, whether lower costs, higher revenue, improved productivity or client experience, better risk management or new products and services, and then measure whether it is achieved. The measure of success needs to move beyond the number of use cases, licences or employees using the technology, to where AI genuinely improves the economics or effectiveness of an organisation.
The economics can also change sharply as AI scales. One technology investor at the forum described how its AI costs rose 58-fold in a year as usage expanded, before optimisation cut them by 90% while maintaining product quality. The economics of a pilot may look very different at enterprise scale.
We should equally be willing not to proceed with AI initiatives that cannot demonstrate sufficient value. Not every business problem requires an AI solution, and at the JSE we start with the business outcome before considering the technology best suited to achieve it. We have deferred initiatives where questions about data, legal considerations, implementation costs or the underlying business case have not been resolved. Experimentation should not create an obligation to implement.
Governance must keep pace
Governance is just as important, particularly as companies begin to introduce agentic AI. BCG found that 42% of companies expect AI agents to act autonomously, without human approval, by 2030, yet only 5% have the relevant controls in place.
The governance challenge changes fundamentally when AI moves from providing information and recommendations to taking actions on behalf of an organisation. For financial markets this is particularly important, because markets depend on confidence in the integrity of their infrastructure, information and decision-making.
We are confronting this directly at the JSE as we experiment with agentic AI. One initiative is testing how agents could securely interrogate market data, initially using equity-trade data. Before allowing such capabilities to scale, we are testing the identity, access, data-governance and audit controls around them, and limiting outputs to advisory and informational purposes.
The distinction is important. An AI tool that helps an employee research or draft something presents a very different risk from an AI agent capable of taking an action within a market process. As autonomy increases, the boundaries within which AI can operate, the ability to audit its actions and human accountability for the outcomes all need to become correspondingly stronger.
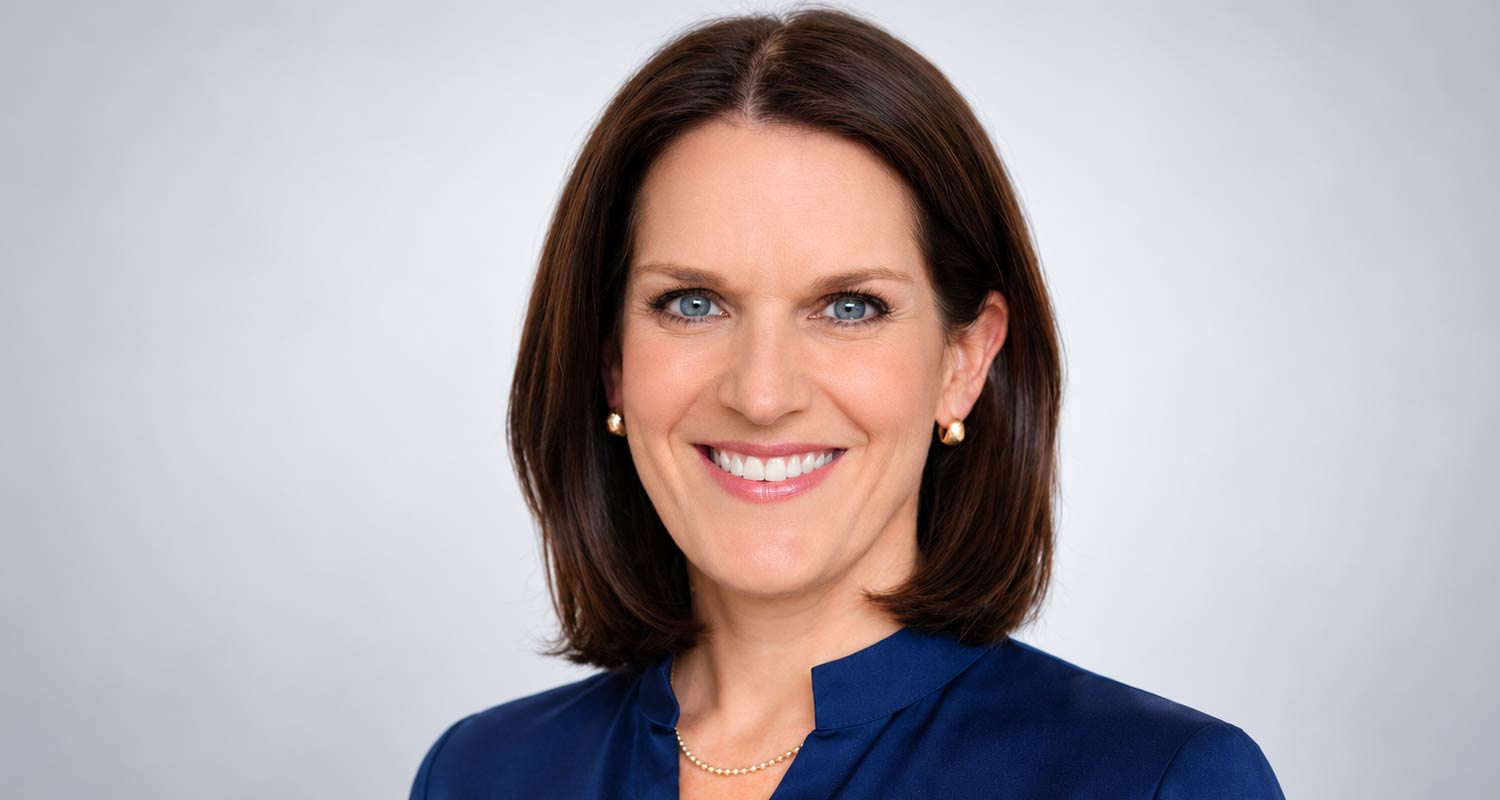
- The author, Alicia Greenwood, is chief operating officer of the JSE