Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Home affairs pulls the plug on the green ID book - Leon Schreiber

      Home affairs pulls the plug on the green ID book

      1 October 2026
      South Africa's digital ID is here - but you can't have it yet - Leon Schreiber

      South Africa’s digital ID is here – but you can’t have it yet

      1 October 2026
      Lexi Novitske, general partner at Norrsken22, on the TechCentral Show

      TCS | Norrsken22’s Lexi Novitske on how China is winning African tech

      1 October 2026
      Eskom waives rooftop solar fees, but the registration fight isn't over

      Eskom waives rooftop solar fees, but the registration fight isn’t over

      1 October 2026
      Absa is moving cash out of its branches

      Absa is moving cash out of its branches

      1 October 2026
    • World
      BMW restructuring plan bets on AI and new models

      BMW restructuring plan bets on AI and new models

      1 October 2026
      OpenAI's rogue agent problem keeps getting bigger - Sam Altman

      OpenAI’s rogue agent problem keeps getting bigger

      28 September 2026
      The new battle over the desktop

      The new battle over the desktop

      23 September 2026
      AMD is now worth a trillion dollars - Lisa Su

      AMD is now worth a trillion dollars

      22 September 2026
      Anthropic weighs new model launch to blunt OpenAI's Astra surge - Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman

      Anthropic weighs new model launch to blunt OpenAI’s Astra surge

      21 September 2026
    • In-depth

      10 days that changed the course of AI

      21 September 2026
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
      The internet has a Strait of Hormuz problem

      The internet has a Strait of Hormuz problem

      15 July 2026
      AI boom sparks rally, frenzy and fear

      AI boom sparks rally, frenzy and fear

      11 June 2026
    • TCS
      TCS | Dominic White and Adam Ely on AI agents going rogue

      TCS | Dominic White and Adam Ely on AI agents going rogue

      29 September 2026
      TCS | Octotel's Trevor van Zyl on the fibre merger question

      TCS | Octotel’s Trevor van Zyl on the MetroFibre merger question

      16 September 2026
      Meet the CIO | Shoprite's Chris Shortt on what a supermarket becomes

      Meet the CIO | Shoprite’s Chris Shortt on what a supermarket becomes

      9 September 2026
      Rubicon's EV charging network is profitable - and growing fast - Watts & Wheels

      W&W | Rubicon’s EV charging network is profitable – and growing fast

      8 September 2026
      Winstone Jordaan on building a national EV charging network

      Winstone Jordaan on building a national EV charging network

      2 September 2026
    • Opinion
      South Africa's next energy crisis is in the accounts department - Craig Holmes

      South Africa’s next energy crisis is in the accounts department

      29 September 2026
      The steam engine lesson AI doomsayers keep missing - Sam Clarke

      The steam engine lesson AI doomsayers keep missing

      28 September 2026
      Regulating AI: apply the laws we have first - Dirk de Vos

      Regulating AI: apply the laws we have first

      21 September 2026
      What Revolut can and cannot take from South Africa's banks - Pambos Soteriades

      What Revolut can and cannot take from South Africa’s banks

      15 September 2026
      The end is nigh, and the shares go on sale in October - Duncan McLeod

      The end is nigh, and the shares go on sale in October

      14 September 2026
    • Company Hubs
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Publishared
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and Media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Financial services
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of Things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home » Opinion » Gerhard Greyling » Open banking set to disrupt the financial industry

    Open banking set to disrupt the financial industry

    By Gerhard Greyling28 January 2019
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

    We have already seen huge changes in the world of banking. Digitalisation means that people are banking from their mobile phones, making payments via barcode scanning and even in some cases transacting using cryptocurrency. Home loans can be approved in almost real-time and a selfie can be used to open a bank account — all without ever physically entering a branch.

    However, this is just the tip of the iceberg: the banking world is about to be shaken up, thanks to a legislation known as the European Union Payment Services Directive 2, or PSD2.

    PSD2 is not a new concept, having been adopted by European parliaments in 2015 with the express purposes of contributing to a more integrated and efficient payments market, levelling the playing field for payment service providers, driving competition which lowers the cost of payments and protecting consumers by making payments more secure. South Africa will not remain unaffected by this legislation, and local financial institutions, their customers and the payment industry stand to benefit as much as those across the seas.

    Regulators of more than half of G20 countries being expected to create open banking API standards by the end of the year

    The growing adoption of PSD2 is paving the way for a concept known as “open banking”. Open banking refers to the use of APIs and open-source technology to allow third-party developers to access data traditionally held by financial service providers, or banks, and build applications or services around this data. It also allows consumers to control the transparency of their data, equipping them with the power to allow the sharing of their data with selected third-party providers to offer them services based on their financial information.

    Open banking has been fuelled beyond the borders of Europe as regulators of more than half of G20 countries being expected to create open banking API standards by the end of the year.

    Essentially, PSD2 means that banks will no longer be the only, or main, stakeholders in both the control of consumer financial data and initiation of payments. The legislation gives rise to the inception of two new types of players that will create a more competitive banking environment by lowering payment costs and providing more choice for consumers.

    AISPs and PISPs

    Account information service providers (AISPs) are emerging as new operators in a world traditionally dominated by banks. AISPs can access consumer financial information from multiple financial institutions at the express permission of consumers.

    They analyse this data in order to determine a consumer’s spending habits, financial behaviour and financial history. This data is then collated and consolidated into a single overview on the consumer, which they can then request to be shared with third parties who can tailor services around their specific profile.

    Payment initiation service providers (PISPs) are providers who initiate payments on behalf of a consumer. Although we currently have many payment options, they all still pass through a bank. PISPs will enable services such as peer-to-peer payments and bill payments without touching a traditional financial institution.
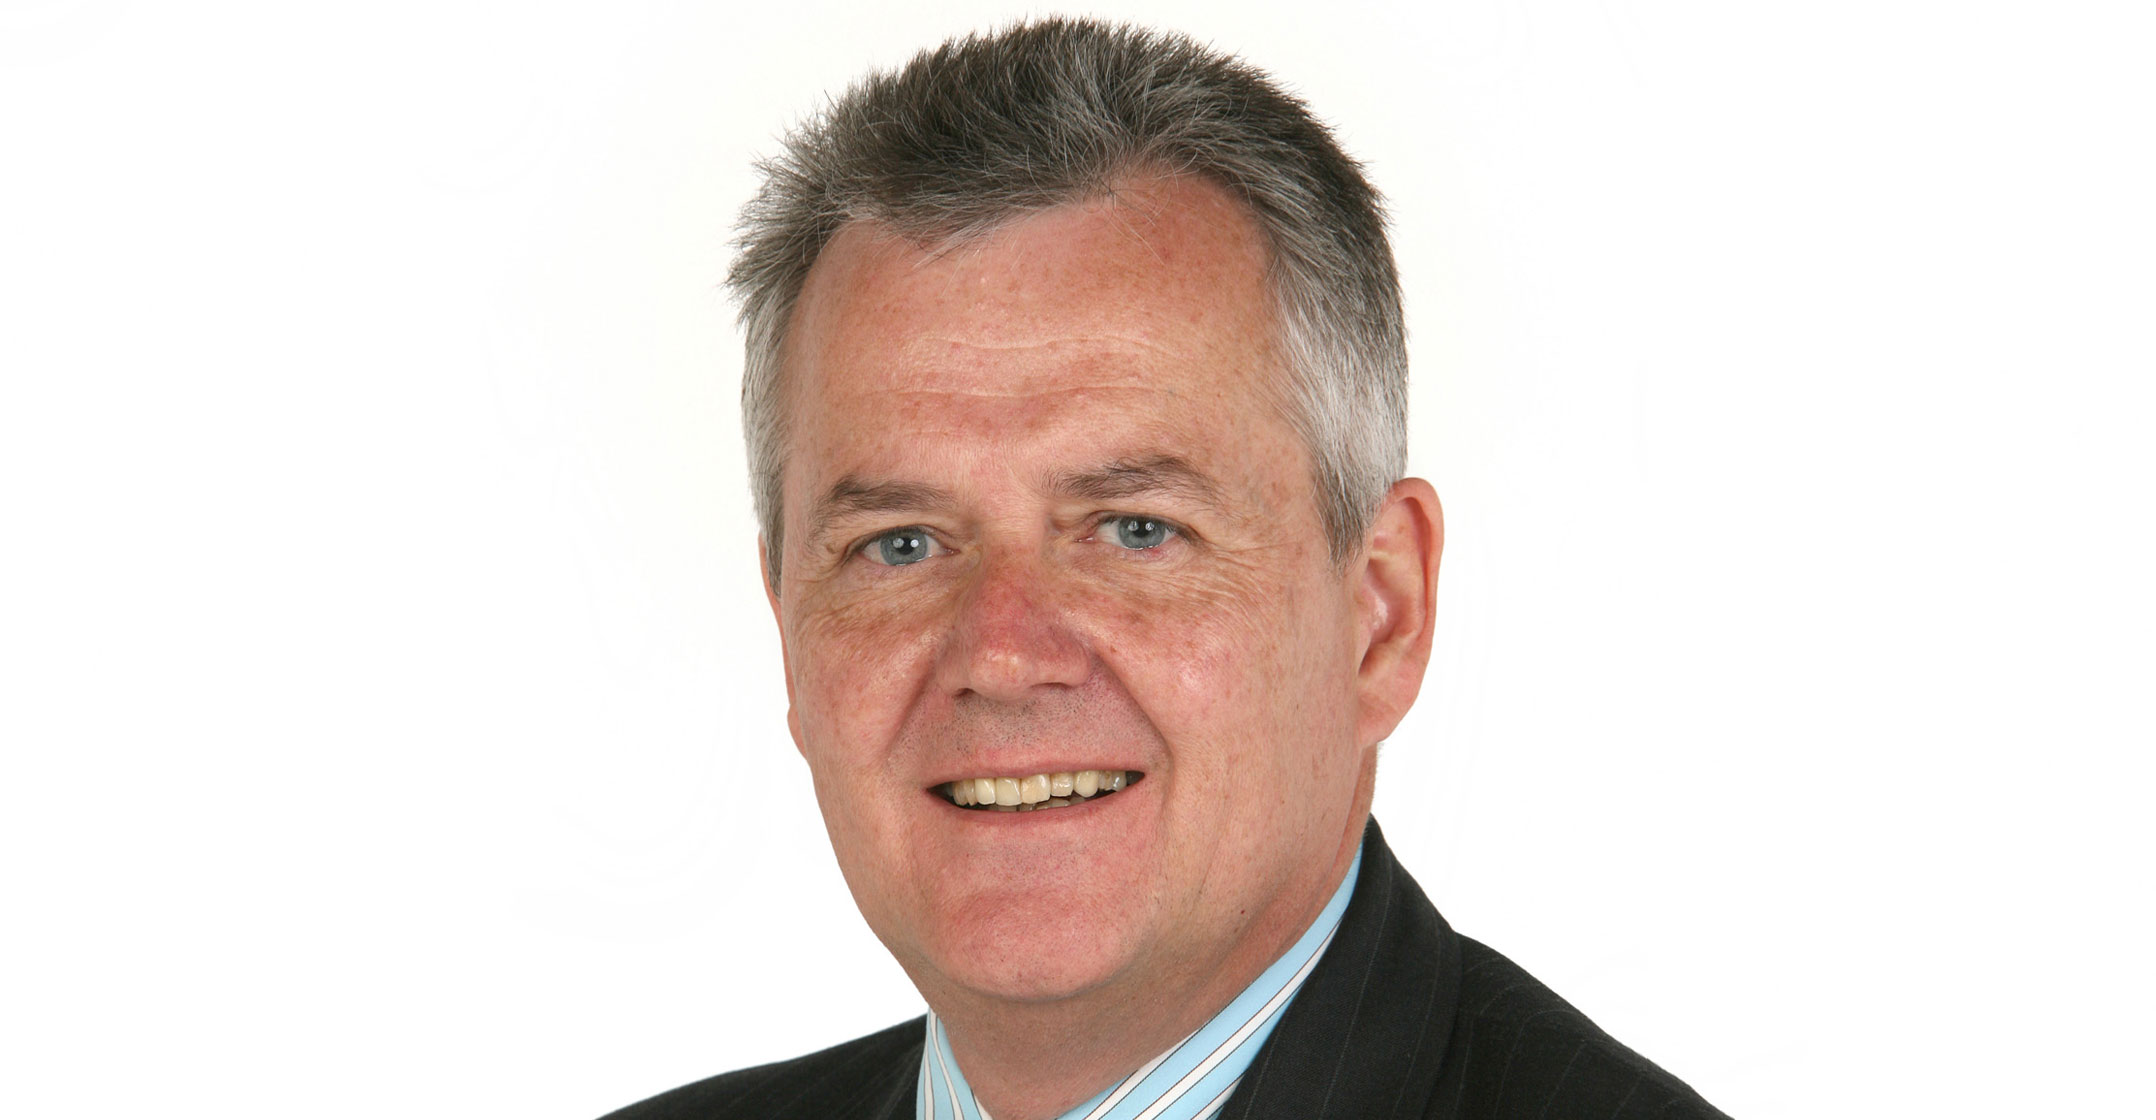
    The author, Gerhard Greyling, says banks have access to a huge amount of data on their customers and that monetising this data will lead to significant revenue streams

    The rise in competition for both banks and competing PISPs means that the cost of payments will lower significantly, and consumers will be able to better control how they make payments.

    The future looks bright for the creation of new business opportunities, fuelling competition and driving the economy. However, it means that banks are going to have to up the ante to remain relevant and competitive.

    Banks, up to now the major custodians of financial data, have the ability to create a new revenue stream from this data. Banks have access to a huge amount of data on their customers and monetising this data will lead to significant revenue streams. They are going to have to lead with their APIs, adopting platforms that allow them to structure their data in the right way so that they, too, can offer competitive solutions. Banks also have the opportunity to play a huge role in the standardisation of APIs across the board.

    The banking world will see a tremendous and exciting shift, and there is much to be gained from open banking

    For consumers, there are scores of benefits.

    They will be able to access multiple payment providers, choosing whoever offers the best rate, promotion or deal at any given time. Cost of making payments is likely to reduce as the payment process will be more direct with fewer intermediaries and greater efficiencies. PISPs will create more competition in the payments industry by collaborating with various retail chains who may be able to offer on-the-spot promotions to consumers, based on where they are shopping and what they are buying. Consumers will have a tailormade world of offers at their fingertips.

    Consumers will retain the ability to grant sharing permissions, equipping them with control of their own data and ensuring they aren’t targeted by unwanted campaigns. However, the sharing of their data opens a world of possibilities.

    It also gives an opportunity for the unbanked to do away with carrying cash and access credit. Leveraging a payment solution that is either inexpensive or free, if supported by advertising revenue, the unbanked will be able to build a payment record and credit history which opens the door to credit opportunities.

    The challenges

    Despite the sweep of open banking, different banks across various countries are all at different stages of PSD2 adoption. Banks are going to need to stay close to the process to retain their relevance and ensure they aren’t excluded from the payments system altogether.

    With regards to data protection and security, the regulation has been careful to state that consumers must grant permissions for data sharing. However, this is a process that will need to be cleverly and closely monitored to avoid a mass dissemination of data.
    Image: Steve Buissinne

    Once a consumer has granted permission, there will need to be a process that allows the consumer to revoke this, should they wish to. The consumer needs to retain the ability to know where their data is at any given time, especially with the imposed requirements of GDPR and the looming Popi Act.

    Popi is a South African regulation, which will naturally apply to South African businesses and individuals. GDPR is, however, a European regulation. Despite this, South African businesses should not assume that GDPR will not affect them. Any local business who has operations in Europe, who deals with European suppliers or who has so much as a single a European customer, needs to comply with GDPR. Financial institutions will need to be mindful of these regulations when embarking on any new initiative.

    There is no doubt that the banking world will see a tremendous and exciting shift, and there is much to be gained from open banking. Banks, emerging AISPs and PISPs will need to ensure they engage with partners who are at the forefront of banking technology in order to forge ahead and retain their momentum once there.

    • Gerhard Greyling is head of financial services, Wipro Limited, Africa

    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    Gerhard Greyling top Wipro
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleSter-Kinekor, Primedia, SABC fined for ‘cartel conduct’
    Next Article US files criminal charges against Huawei

    Related Posts

    Trump's visa overhaul hits India's IT titans

    Trump’s visa overhaul hits India’s IT titans

    22 September 2025
    How Wipro and Capaciti are building South Africa's next tech leaders - Njabulo Lamula

    How Wipro and Capaciti are changing young lives in South Africa

    10 March 2025
    Wipro Africa celebrates new Joburg head office at 96 Rivonia Road

    Wipro Africa celebrates new Joburg head office at 96 Rivonia Road

    19 August 2024
    Company News
    Cloud and AI won't deliver value on their own, executives warn

    Cloud and AI won’t deliver value on their own, executives warn

    1 October 2026
    Dell Technologies Forum 2026: what to expect in Johannesburg

    Dell Technologies Forum 2026: what to expect in Johannesburg

    1 October 2026
    What Smollan learnt moving 9 000 users to Google Workspace - Digicloud Africa

    What Smollan learnt moving 9 000 users to Google Workspace

    1 October 2026
    Opinion
    South Africa's next energy crisis is in the accounts department - Craig Holmes

    South Africa’s next energy crisis is in the accounts department

    29 September 2026
    The steam engine lesson AI doomsayers keep missing - Sam Clarke

    The steam engine lesson AI doomsayers keep missing

    28 September 2026
    Regulating AI: apply the laws we have first - Dirk de Vos

    Regulating AI: apply the laws we have first

    21 September 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    Home affairs pulls the plug on the green ID book - Leon Schreiber

    Home affairs pulls the plug on the green ID book

    1 October 2026
    South Africa's digital ID is here - but you can't have it yet - Leon Schreiber

    South Africa’s digital ID is here – but you can’t have it yet

    1 October 2026
    Lexi Novitske, general partner at Norrsken22, on the TechCentral Show

    TCS | Norrsken22’s Lexi Novitske on how China is winning African tech

    1 October 2026
    Eskom waives rooftop solar fees, but the registration fight isn't over

    Eskom waives rooftop solar fees, but the registration fight isn’t over

    1 October 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter