Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Vodacom targets satellite-to-phone service in South Africa next year

      Vodacom targets satellite-to-phone service in South Africa next year

      10 November 2026
      Vodacom eyes SA and Kenya for AI data centre hubs after Egypt - Shameel Joosub

      Vodacom eyes SA and Kenya for AI data centre hubs after Egypt

      10 November 2026
      Eskom chairman Mteto Nyati and energy minister Kgosientsho Ramokgopa speak to the media in Irene, Pretoria

      South Africa’s first new nuclear reactors could be online by 2036

      10 November 2026
      Comsol's 5G network pricing comes into view

      Comsol’s 5G network pricing comes into view

      10 November 2026
      Safaricom ruling tripped default clauses in Vodacom's loans

      Safaricom ruling tripped default clauses in Vodacom’s loans

      10 November 2026
    • World
      John Ternus faces first big test as Apple CEO - John Ternus

      John Ternus faces first big test as Apple CEO

      2 November 2026
      Alleged Israeli spy company heavily targeted Starlink users

      How online ads were used to hunt Starlink users

      28 October 2026
      Anthropic's IPO stands alone

      Anthropic’s IPO stands alone

      23 October 2026
      PHP flaws trigger global scramble as hackers pounce

      PHP flaws trigger global scramble as hackers pounce

      22 October 2026
      OpenAI turns the tables on Apple in trade secrets fight

      OpenAI turns the tables on Apple in trade secrets fight

      15 October 2026
    • In-depth
      Ducking hell: inside Apple's hidden list of words the iPhone won't suggest

      Ducking hell: inside Apple’s hidden list of words the iPhone won’t suggest

      6 November 2026
      Why investors are souring on Netflix

      Why investors are souring on Netflix

      22 October 2026

      10 days that changed the course of AI

      21 September 2026
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
    • TCS
      TCS+ | Old Mutual's Celiwe Ross on leading people through AI - Old Mutual

      TCS+ | Old Mutual’s Celiwe Ross on leading people through AI

      6 November 2026
      TCS+ | How the Apple ecosystem drives productivity for SMEs - Sudesh Pillay iStore and Kevin McLennan

      TCS+ | How the Apple ecosystem drives productivity for SMEs

      6 November 2026
      TCS+ | Vox on AI, data rules and omnichannel communication for SMEs

      TCS+ | Vox on AI, data rules and omnichannel communication for SMEs

      26 October 2026
      TCS | The Cape Town firm quietly connecting Eskom, Pep and 6 000 ATMs - Réan van Niekerk, Metacom

      TCS | The Cape Town firm quietly connecting Eskom, Pep and 6 000 ATMs

      23 October 2026
      TCS+ | Boards are underestimating the cost of a cyberattack, says Arctic Wolf - Jason Oehley and Andre Den Hond

      TCS+ | Boards are underestimating the cost of a cyberattack, says Arctic Wolf

      22 October 2026
    • Opinion
      Icasa's Sim rules need a privacy backstop - Lloyd Matthew and Heinz Vollmer

      Icasa’s Sim rules need a privacy backstop

      5 November 2026
      AI's boardroom honeymoon is over - Gary Stocks

      AI’s boardroom honeymoon is over

      22 October 2026
      Before South Africa licenses Starlink, it should look at Ukraine - Duncan McLeod

      Before South Africa licenses Starlink, it should look at Ukraine

      21 October 2026
      Nonkqubela Thathakahle Jordan-Dyani

      Why cybersecurity is now a national security issue for South Africa

      15 October 2026
      When a machine can choose, who does it become? Fanie van Rooyen

      When a machine can choose, who does it become?

      9 October 2026
    • Company News
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Publishared
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Fintech and payments
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home » In-depth » Challenge to banks as lending goes social

    Challenge to banks as lending goes social

    By Lynley Donnelly29 April 2014
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

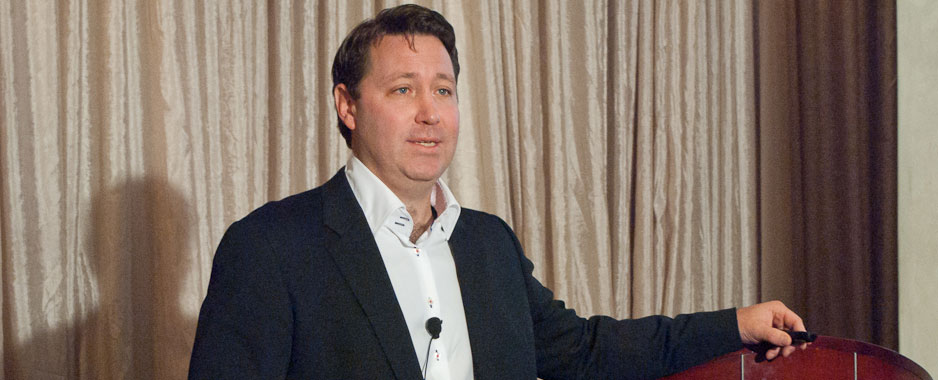
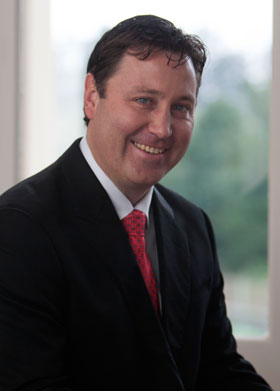
    Sean Emery
    Sean Emery

    South Africans have been doing it for generations. Social lending, familiar to many in the form of groups like stokvels, has been a hallmark of how many people make do, outside of formal financial networks.

    Thanks to the Web however, social lending, also known as peer-to-peer (P2P) lending, has begun to take off in developed countries, with the rise of platforms such as Lending Club in the US and Zopa in Britain.

    Similar P2P platforms have begun to spring up on South African soil, with the newest, Lendico, launched two weeks ago by African Internet Holding (AIH). It follows on the heels of home-grown RainFin, which has attracted such interest from traditional banks that Barclays Africa snapped up a 49% stake in the company earlier this year.

    Players in the industry believe that P2P lending platforms are the long overdue digital challenger to the banking industry, which has so far escaped significant online competition. This is especially true in developed countries where banks’ reputations were sullied by their role in the financial crisis, and many needed huge government bailouts to stay afloat.

    These sites are essentially digital money market places that match borrowers directly with lenders. Without a bank in the middle of the transaction, the interest rates for borrowers and those willing to invest in them and their projects are better. In Lendico’s case it positions itself as a direct “digital alternative to banks”.

    Jeremy Hodara, AIH co-CEO, said P2P platforms have significant potential to leapfrog the traditional brick-and-mortar bank, particularly on the African continent, where AIH has launched a host of online businesses. While these platforms are distinct from banks, they are registered with the National Credit Regulator.

    In the case of Lendico, borrowers register their loan requirement or project on the site for free. Loan projects can be anything from the consolidation of more expensive debt to renovations on a house, money for a wedding or the deposit on a flat. Lendico analyses borrowers’ credit worthiness and determines their interest rates in relation to their risk profile.

    Borrowers are categorised in risk grades — for instance those with good credit records or “A grade” borrowers will pay interest rates of between 7,11% and 8,48%. Lower-grade borrowers with worse credit scores face steeper rates of between 13,7% and 21,56%.

    Lenders can view the loan projects online and bid on whichever projects they prefer, starting with amounts as small as R250.

    Lenders seeking to lend to A-grade borrowers can get returns estimated at between 5,73% and 7,2%, assuming an estimated default rate of somewhere between 1,32% and 1,92% in this class of borrower. Lenders willing to take risks on less credit-worthy individuals, such as E-grade borrowers, get returns of between 11,27% and 19,86%, with a higher estimated default rate of between 6,72% and 13,56%.

    The term of the loans, which can stretch from one to five years, also affects the rate. To facilitate the transactions, Lendico charges between 1% and 3,5%.

    RainFin follows a similar format, screening potential borrowers as well as the instances in which they default, listing poor repayers and initiating collection proceedings against them.

    In RainFin’s case, lenders also bid for a loan, or group of loans, based on criteria such as interest rates and credit risk bands. Borrowers on the site provide an indicative maximum rate that they agree to borrow money at. According to RainFin CEO Sean Emery, the platform suggests a recommended rate that lenders lend money at, based on borrowers’ credit scores. But lenders can agree to lend at the maximum rate agreed to by the borrower, the recommended rate, or a lender can offer to lend at a different rate — although it cannot be more than the maximum rate a borrower agreed to upfront.

    Social lending platforms
    According to Emery, since June 2012, the median interest rate for borrowers has been in the order of 14,1%. One wholesale funder, which helped kick-start the marketplace, holds 42% of the loans. But the wholesale lender aside, the average return for lenders, after bad debt of about 5,2%, is in the region of 9,1%.

    RainFin offers a friend-to-friend platform that exists outside of its credit-scoring universe. It essentially allows people who know and trust one another to lend or borrow from each other. RainFin acts as the intermediary, easing some of the interpersonal strain that comes with mixing financial affairs with friends and family.

    The rates, Emery said, are substantially better than what banks are offering, both to the people who save with them, as well as the people who borrow from them. He pointed out that an individual with a good credit rating and earning a full-time salary, seeking an unsecured loan from a bank, typically ends up paying 13% to 16% interest.

    Those who lack a regular payslip — the self-employed, for instance — are only likely to get loans at around 18% or higher, he argued. Home loans with a 20% deposit come at rates of around 8,5%, car loans at around 14% and credit cards carry rates of around 26%, he said.

    “So on peer-to-peer platforms, if you as a lender lend to consumers with an [entry level] credit score, who have an average of a 4% default and you lend to them at 14% interest, you will have net earnings of 10% versus 5,5% at a bank, and they will pay a fee of 14% versus 19%,” said Emery.

    Internationally the growth of social lending platforms has risen rapidly.

    Increasingly, large financial sector players are taking notice of these platforms. Last year, the Financial Times reported how three investment banks — Bank of America, Citigroup and JPMorgan Chase — took out a collective £235 000 worth of loans from Lending Club, the largest social lending marketplace in the US.

    In May last year, Lending Club announced that Google had bought a minority stake in the company, through a US$125m secondary investment round, which allows new and existing investors to acquire shares from existing investors. According to Lending Club statistics, it has facilitated just over $4bn in loans and it has more than doubled loan volumes each year since it began in May 2007. According to UK-based Zopa’s website, loans made via the platform stand at over £515m.

    Hodara believes that although mainstream banks may be eyeing the P2P sector, any attempts to co-opt it are unlikely to work. “They won’t do it like a real, pure player,” he said. The history of e-commerce has shown that many traditional offline operators have struggled or failed to take their brands online, Hodara noted. Nevertheless, companies such as Lendico do need the skill and expertise of traditional financial players for the business to succeed, he said.

    Drawing the eye of regulators
    With the evolution of these platforms, however, has come the watchful eye of regulators. In 2008, after being ordered to halt business, Lending Club and P2P lender Prosper were required to list their loans as securities in the US with the Securities and Exchange Commission. UK financial watchdog the Financial Conduct Authority introduced new rules governing social lending platforms in April.

    Locally, Emery admits there was initial uncertainty over how to treat RainFin’s operations from a regulatory standpoint. As RainFin does not take deposits but rather holds money in trust on behalf of other parties in the same way an estate agent or legal firm might; and as it does not raise money from the public for the sole purpose of on-lending, it does not require a banking licence. According to Emery it was decided, however, that the platform, and any transactions concluded on the platform, should operate under the principals of the National Credit Act, with responsible lending foremost in mind.

    In the beginning, distressed borrowers dominated the platform, but this is slowly changing, said Emery. Increasingly, users are creditworthy individuals who don’t get regular payslips. As such, they fall outside of bank lending criteria, which he believes is heavily reliant on the “overlent” payslip market.

    RainFin lenders, meanwhile, are entrepreneurial, looking for diverse investment opportunities and are attracted by the idea that they are lending to people much like themselves, rather than merely making a “massive bank bigger”.

    But facilitating unsecured credit is simply “scratching the surface”, said Emery. RainFin is exploring introducing secured lending platforms, where assets such as cars can be provided as security. With Barclays on board, RainFin is planning to launch several different P2P product categories, from unsecured to secured loans, as well as small business loans and loans for entrepreneurs. With this in mind, he is hopeful that large asset managers could be convinced to participate.

    Emery is mindful that RainFin is still a growing start-up; nevertheless, the aim is to “have a community of people who can get finance anywhere else in South Africa, but they [are] choosing to get finance with us because they want to be part of this revolution”.

    Neither the South African Reserve Bank nor the National Credit Regulator responded to requests for comment.  — (c) 2014 Mail & Guardian

    • Visit the Mail & Guardian Online, the smart news source
    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    African Internet Holding AIH Lendico RainFin Sean Emery
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleSo long, and thanks for all the plusses
    Next Article Cell C hits back with new prepaid deals

    Related Posts

    Online peer lending could boost SMEs

    3 September 2014

    Barclays buys into start-up RainFin

    6 March 2014

    RainFin: loans without banks

    3 July 2012
    Company News
    The hidden risks of fragmented IT and unenforced SLAs - ITC Systems Durban

    The hidden risks of fragmented IT and unenforced SLAs

    10 November 2026
    Why AI-powered customer experience will decide South Africa's festive retail winners - CM.com

    Why AI-powered customer experience will decide South Africa’s festive retail winners

    10 November 2026
    Traditional QA undermines modern customer experience - Martie de Beer, Telviva

    Traditional QA undermines modern customer experience

    10 November 2026
    Opinion
    Icasa's Sim rules need a privacy backstop - Lloyd Matthew and Heinz Vollmer

    Icasa’s Sim rules need a privacy backstop

    5 November 2026
    AI's boardroom honeymoon is over - Gary Stocks

    AI’s boardroom honeymoon is over

    22 October 2026
    Before South Africa licenses Starlink, it should look at Ukraine - Duncan McLeod

    Before South Africa licenses Starlink, it should look at Ukraine

    21 October 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    The hidden risks of fragmented IT and unenforced SLAs - ITC Systems Durban

    The hidden risks of fragmented IT and unenforced SLAs

    10 November 2026
    Why AI-powered customer experience will decide South Africa's festive retail winners - CM.com

    Why AI-powered customer experience will decide South Africa’s festive retail winners

    10 November 2026
    Vodacom targets satellite-to-phone service in South Africa next year

    Vodacom targets satellite-to-phone service in South Africa next year

    10 November 2026
    Vodacom eyes SA and Kenya for AI data centre hubs after Egypt - Shameel Joosub

    Vodacom eyes SA and Kenya for AI data centre hubs after Egypt

    10 November 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter