Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Rogue AI agents are already loose inside big companies

      Rogue AI agents are already loose inside big companies

      23 September 2026

      Africa’s start-ups are building on Chinese AI

      23 September 2026
      London's IPO drought could be broken by an African fintech - Airtel Money

      London’s IPO drought could be broken by an African fintech

      23 September 2026
      Altron earnings climb as platforms carry the group

      Altron earnings climb as platforms carry the group

      23 September 2026
      The new battle over the desktop

      The new battle over the desktop

      23 September 2026
    • World
      Anthropic weighs new model launch to blunt OpenAI's Astra surge - Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman

      Anthropic weighs new model launch to blunt OpenAI’s Astra surge

      21 September 2026
      Hackers hack hackers: ShinyHunters seizes cl0p's dark web site

      Hackers hack hackers as dark web feud erupts

      21 September 2026
      Film piracy malware is reaching corporate machines

      Film piracy malware is reaching corporate machines

      21 September 2026
      Crypto's big bet fails as US senate sinks Clarity Act

      Crypto’s big bet fails as US senate sinks Clarity Act

      16 September 2026
      'This is not circular': Jensen Huang defends $3.5-billion MediaTek deal

      ‘This is not circular’: Jensen Huang defends $3.5-billion MediaTek deal

      2 September 2026
    • In-depth
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
      The internet has a Strait of Hormuz problem

      The internet has a Strait of Hormuz problem

      15 July 2026
      AI boom sparks rally, frenzy and fear

      AI boom sparks rally, frenzy and fear

      11 June 2026
      Every plug-in hybrid on sale in South Africa, ranked by price - Lamborghini Temerario

      Every plug-in hybrid on sale in South Africa, ranked by price

      7 June 2026
    • TCS
      TCS | Octotel's Trevor van Zyl on the fibre merger question

      TCS | Octotel’s Trevor van Zyl on the MetroFibre merger question

      16 September 2026
      Meet the CIO | Shoprite's Chris Shortt on what a supermarket becomes

      Meet the CIO | Shoprite’s Chris Shortt on what a supermarket becomes

      9 September 2026
      Rubicon's EV charging network is profitable - and growing fast - Watts & Wheels

      Rubicon’s EV charging network is profitable – and growing fast

      8 September 2026
      Winstone Jordaan on building a national EV charging network

      Winstone Jordaan on building a national EV charging network

      2 September 2026
      Watts & Wheels S1E8: 'Tesla lands in Africa, just not here'

      Watts & Wheels S1E8: ‘Tesla lands in Africa, just not here’

      24 August 2026
    • Opinion
      Regulating AI: apply the laws we have first - Dirk de Vos

      Regulating AI: apply the laws we have first

      21 September 2026
      The end is nigh, and the shares go on sale in October - Duncan McLeod

      The end is nigh, and the shares go on sale in October

      14 September 2026
      The fragile joint in the Capitec machine - Pambos Soteriades

      The R197-billion market the banks can’t reach

      25 August 2026
      South African tech's compounding debt problem - Jannie van Zyl

      Management consulting as we know it is over

      21 August 2026
      South African tech's compounding debt problem - Jannie van Zyl

      The most dangerous customer is the quiet one

      10 August 2026
    • Company Hubs
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and Media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Financial services
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of Things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home » In-depth » Why Naspers is not a good investment

    Why Naspers is not a good investment

    By Editor15 May 2014
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

    Victor-von-Reiche-180Naspers was the darling of the JSE in 2013, contributing a full 4,2% of the total market performance of 18% last year. But we believe that, although it may be a great business, Naspers does not represent a good investment.

    Investors seem to be pricing the share for perfection, and then some. Eager to gain access to the Chinese market, via Naspers’s holding in the social media firm Tencent, investors have bid the stock up to a price to earnings (p:e) multiple of 61,5x. Naspers has had an average return on equity of 12% over the past five years, and is on a dividend yield of just 0,2%.

    At closing market prices on 12 May, Naspers’s 34% stake in Tencent was worth R427bn against its own market capitalisation of R453bn, representing 94% of total value. If one accepts Tencent as fairly valued, then Naspers does present an interesting investment case, with the rump of its assets in Mail.ru, pay television and e-commerce on offer for very little.

    We believe, though, that you have to assess the intrinsic value of Tencent (as opposed to using the market price) to better understand the valuation around Naspers, given the fact that Naspers has become a proxy for Tencent, with Naspers’s market price movement reflecting what happens in Hong Kong. The key question therefore becomes the following: what does Tencent need to deliver over the next 10 years to justify its current valuation?
    Andrew-Dittberner-180We used a free cash flow approach with the most recent financial data available from Tencent to estimate this. Based on our estimates, Tencent will need to grow operating income (or earnings before interest and tax) at a compound annual growth rate of 24,6% over the next 10 years in nominal terms. What is worth further emphasis, is that we assume that this will be very high-quality growth — in other words, that Tencent will maintain its current return on invested capital (ROIC) of 55% over this period. Seen against the cost of capital of 9,5%, we can’t help but feel that this spread will close in coming years as competition intensifies, which will erode margins and necessitate increased investment. In turn, lower ROIC will require even higher growth rates to justify the current valuation.

    Finally, at current levels, we estimate that investors are valuing Tencent at an intrinsic p:e of 48 times, with 80% of the valuation stemming from growth investments that the company will make over the next decade and 20% of the valuation from investments the business has already made. In other words, Naspers is priced for growth — and quite spectacular growth at that. We prefer to buy businesses where most of the value is explained by cash flows from investments the company has already made and where growth is given to us as a free option.

    For these reasons, we believe that a company such as SinoMedia makes much better investment sense than Naspers or Tencent. A relatively small business, SinoMedia is listed in Hong Kong and operates primarily in China. The stock has been listed since 2008, having been formed in 2005, and has built up 1 600 clients in the region.

    SinoMedia is largely a wholesale purchaser of advertising space from the television and broader media sector in mainland China, which it then sells on to its various clients. SinoMedia owns the rights to CNBC in China as well as CCTV — the company has 39 501 minutes of advertising time to sell — while clients include the likes of BMW, Ping AN Insurance and Sony.
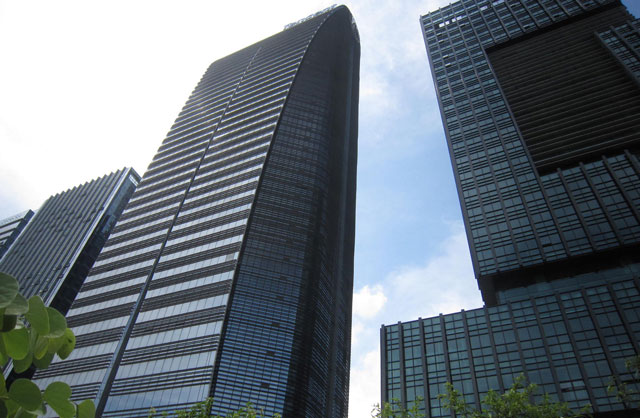
    Tencent's headquarters in Shenzhen, China (image: Dmitry Lysenko)
    Tencent’s headquarters in Shenzhen, China (image: Dmitry Lysenko)

    SinoMedia also boasts three other divisions: integrated brand communications; content production (notably TV advertisements); and new media investment and integration. In addition, SinoMedia owns stakes in several Internet-based companies, so it is increasingly encroaching on the Tencent digital space.

    The stock offers many of what we consider to be key investment ingredients, including a return on equity of 35%, net income growth of 25%/year over the last five years and undemanding valuation multiples. The latter comes in the form of an earnings multiple of 8,1x and a trailing dividend yield of 2,1%.

    Thematically, this stock affords us the opportunity to gain exposure to the rapidly growing Chinese media market at a compelling price. This is explained, in part, by the fact that the counter is not listed on the Chinese stock exchange and has therefore not captured all of the attention that many other shares have. As always, Cannon’s investment approach emphasises buying good businesses, but at the right price.

    • Victor von Reiche is senior investment analyst at Cannon Asset Managers and Andrew Dittberner is senior investment manager at the same firm
    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    Andrew Dittberner Cannon Assets Managers Naspers SinoMedia Tencent Victor von Reiche
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleNo plans to sell Autopage: Altron
    Next Article Evolutionary leftovers

    Related Posts

    WeTransfer founder joins Prosus in AI leadership shake-up

    WeTransfer founder joins Prosus in AI leadership shake-up

    22 September 2026
    Sixty60 now drives more than a third of Shoprite's growth - Neil Schreuder

    Sixty60 now drives more than a third of Shoprite’s growth

    12 August 2026
    Big changes to Vodacom's board - Segun Ogunsanya

    Big changes to Vodacom Group board

    12 August 2026
    Company News
    The Courier Guy enhances customer engagement with Telviva

    The Courier Guy enhances customer engagement with Telviva

    23 September 2026
    Pinnacle takes its channel to Mauritius for TechScape 2026

    Pinnacle takes its channel to Mauritius for TechScape 2026

    23 September 2026
    Why true customer enablement starts on the inside - Backspace Technologies COO Graeme Thomson

    Why true customer enablement starts on the inside

    23 September 2026
    Opinion
    Regulating AI: apply the laws we have first - Dirk de Vos

    Regulating AI: apply the laws we have first

    21 September 2026
    The end is nigh, and the shares go on sale in October - Duncan McLeod

    The end is nigh, and the shares go on sale in October

    14 September 2026
    The fragile joint in the Capitec machine - Pambos Soteriades

    The R197-billion market the banks can’t reach

    25 August 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    Rogue AI agents are already loose inside big companies

    Rogue AI agents are already loose inside big companies

    23 September 2026

    Africa’s start-ups are building on Chinese AI

    23 September 2026
    London's IPO drought could be broken by an African fintech - Airtel Money

    London’s IPO drought could be broken by an African fintech

    23 September 2026
    Altron earnings climb as platforms carry the group

    Altron earnings climb as platforms carry the group

    23 September 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter