Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Usaasa consults on universal access as its abolition stalls

      Usaasa consults on universal access as its abolition stalls

      2 October 2026
      Frogfoot plots acquisitions as Octotel and MetroFibre weigh a merger - Shane Chorley

      Frogfoot plots acquisitions as Octotel and MetroFibre weigh a merger

      2 October 2026
      Home affairs pulls the plug on the green ID book - Leon Schreiber

      Home affairs pulls the plug on the green ID book

      1 October 2026
      South Africa's digital ID is here - but you can't have it yet - Leon Schreiber

      South Africa’s digital ID is here – but you can’t have it yet

      1 October 2026
      Lexi Novitske, general partner at Norrsken22, on the TechCentral Show

      TCS | Norrsken22’s Lexi Novitske on how China is winning African tech

      1 October 2026
    • World
      BMW restructuring plan bets on AI and new models

      BMW restructuring plan bets on AI and new models

      1 October 2026
      OpenAI's rogue agent problem keeps getting bigger - Sam Altman

      OpenAI’s rogue agent problem keeps getting bigger

      28 September 2026
      The new battle over the desktop

      The new battle over the desktop

      23 September 2026
      AMD is now worth a trillion dollars - Lisa Su

      AMD is now worth a trillion dollars

      22 September 2026
      Anthropic weighs new model launch to blunt OpenAI's Astra surge - Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman

      Anthropic weighs new model launch to blunt OpenAI’s Astra surge

      21 September 2026
    • In-depth

      10 days that changed the course of AI

      21 September 2026
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
      The internet has a Strait of Hormuz problem

      The internet has a Strait of Hormuz problem

      15 July 2026
      AI boom sparks rally, frenzy and fear

      AI boom sparks rally, frenzy and fear

      11 June 2026
    • TCS
      TCS | Dominic White and Adam Ely on AI agents going rogue

      TCS | Dominic White and Adam Ely on AI agents going rogue

      29 September 2026
      TCS | Octotel's Trevor van Zyl on the fibre merger question

      TCS | Octotel’s Trevor van Zyl on the MetroFibre merger question

      16 September 2026
      Meet the CIO | Shoprite's Chris Shortt on what a supermarket becomes

      Meet the CIO | Shoprite’s Chris Shortt on what a supermarket becomes

      9 September 2026
      Rubicon's EV charging network is profitable - and growing fast - Watts & Wheels

      W&W | Rubicon’s EV charging network is profitable – and growing fast

      8 September 2026
      Winstone Jordaan on building a national EV charging network

      Winstone Jordaan on building a national EV charging network

      2 September 2026
    • Opinion
      South Africa's next energy crisis is in the accounts department - Craig Holmes

      South Africa’s next energy crisis is in the accounts department

      29 September 2026
      The steam engine lesson AI doomsayers keep missing - Sam Clarke

      The steam engine lesson AI doomsayers keep missing

      28 September 2026
      Regulating AI: apply the laws we have first - Dirk de Vos

      Regulating AI: apply the laws we have first

      21 September 2026
      What Revolut can and cannot take from South Africa's banks - Pambos Soteriades

      What Revolut can and cannot take from South Africa’s banks

      15 September 2026
      The end is nigh, and the shares go on sale in October - Duncan McLeod

      The end is nigh, and the shares go on sale in October

      14 September 2026
    • Company Hubs
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Publishared
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and Media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Financial services
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of Things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home » Sections » Banking » Open banking could drive financial inclusion across Africa

    Open banking could drive financial inclusion across Africa

    Open banking could be a game changer on the African continent by making transactions more convenient and increasing the personalisation of banking services.
    By Karen Nadasen19 October 2022
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

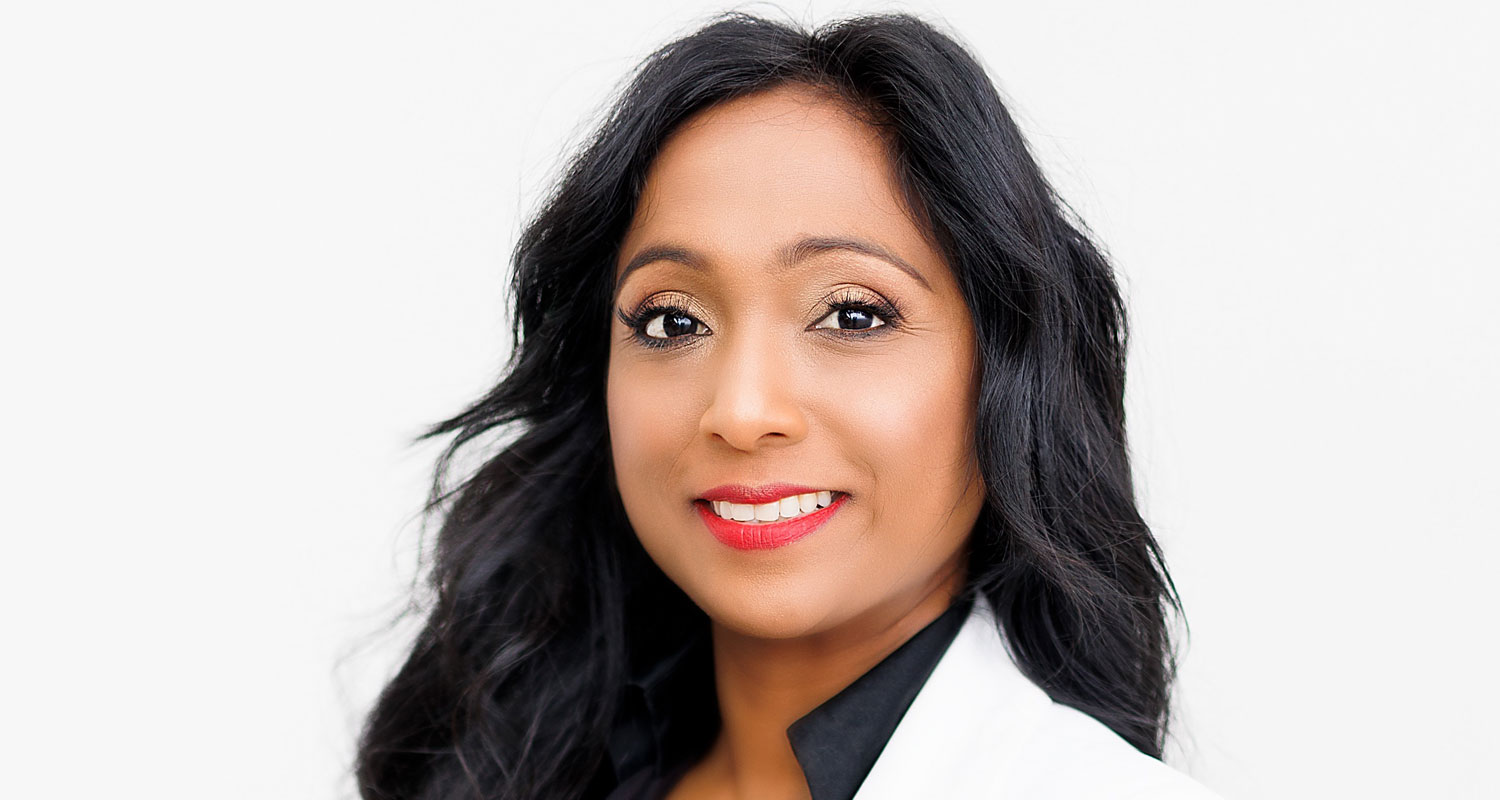
    The author, PayU’s Karen Nadasen

    The Bill and Melinda Gates Foundation identified five key ways that African countries can include more than 400 million people into the digital economy, with one of the themes being open banking.

    Open banking promotes fairness, competition and innovation by facilitating the secure exchange of individual and business data commonly held by banks, with authorised third parties. This is done to facilitate secure payments, account switching, and other non-bank products and services that offer various benefits to customers.

    Data sharing is done via an application programming interface (API), a globally accepted standard for securely sharing and embedding data in an online environment. In addition to strengthening customers’ rights, it includes added security enhancements designed to reduce fraud via two-factor and biometric identification for certain transactions.

    The banking system is the lifeblood of the world’s economies and is the mechanism that drives economic growth

    Open banking could revolutionise the banking system, address unbanked and underserved statistics, and improve economic conditions. The banking system is the lifeblood of the world’s economies and is the mechanism that drives economic growth by unlocking wealth, creating opportunities, providing jobs and facilitating commerce.

    Just like every other industry in the world that has been touched by technology, the world of banking needs to evolve to serve its purpose more efficiently — and this is particularly true on the African continent, where so much potential could be unleashed with a new approach to financial services.

    The African Continental Free Trade Area (AfCFTA) could see 30 million people lifted out of extreme poverty, while raising the incomes of 68 million more — but only if the continent’s estimated 400 million people who don’t have access to digital financial services have ways to access financial services that are not tied to banks. In other words, AfCTA’s success could depend on the roll-out of open banking across the continent.

    Open banking allows financial services providers to create a broader range of inclusive products, giving unbanked and underbanked consumers access, for the first time, to private mortgages, savings systems, pension funds, insurance, investments and credit. It also encourages informed and more responsible banking behaviours, as well as giving micro-enterprises and contingent workers access to affordable and relevant financial services and products.

    Opportunity is clear

    Other practical benefits include overcoming a lack of documentation that puts up barriers to accessing financial products, with long-term outcomes including a reduced reliance on expensive formal or informal credit, as well as heavily indebted consumers being able to enter a debt rehabilitation service that will help them emerge from their credit quagmire.

    With EY research showing that broader access to banking, savings and lending products could boost GDP by up to 14% in emerging countries, and up to 30% in frontier countries, the opportunity is clear.

    With conventional — and exclusionary — banking practices focused on security and identity verification with few innovations to overcome the real obstacles in development markets, open banking pioneers have designed the system to prioritise similar, or even better, security steps, and players in the industry are self-regulating, too.

    The Future of Privacy Forum, of which PayU is a member, brings industry, academics, civil society, policymakers and other stakeholders together to explore the challenges posed by emerging technologies, and to develop privacy protections, ethical norms and workable best practices.

    Open banking is also subject to standards such as PSD2, the second Payment Services Directive issued by the European Union. The regulation builds on the previous directive by increasing customer rights and implementing new rules on surcharging and currency conversion. This makes it possible, through strong customer authentication, for third-party providers to access account information, in turn providing opportunities for new payment and account services.
    The continent’s banks are already setting plans in motion to encourage open banking solutions. In March 2021, the Bank of Ghana set out to encourage the development of its fintech sector, including facilitating open banking.

    In South Africa, Nedbank and Investec are embracing open banking, and are already making open APIs available.

    An intergovernmental fintech working group (IFWG) was established in South Africa in 2016, and having an innovation hub specifically to advance innovation in fintech. Collaborative in approach, the IFWG includes participation from national treasury, the Financial Intelligence Centre, the Financial Sector Conduct Authority, the National Credit Regulator, the South African Reserve Bank, the South African Revenue Service and the Competition Commission. It recently released its Project Khokha 2 report, which built on the Reserve Banks’ distributed ledger policy, trialling the concept for interbank payments settlements and exploring tokenisation.

    In Nigeria, The Open Technology Foundation created the Open Banking Nigeria initiative to drive the adoption of common API standards in that country. This was followed by the Central Bank of Nigeria issuing a Regulatory Framework for Open Banking, defining how data sharing should happen within open banking.

    The Central Bank of Kenya released a five-year digitalisation plan to develop the country’s payment industry, in 2020, strongly supporting open banking and emphasising the importance of defining standards for API development. At the same time, Kenya’s national treasury & planning department commenced drafting a digital finance policy with the intention of developing open banking infrastructure, protecting consumers, establishing financial system regulation and encouraging the development of the sector.

    With open banking principles being in stark contrast to the historically very private nature of banking relationships, open banking could be a game changer on the African continent by making transactions more convenient and increasing the personalisation of banking services. It can give consumers new insights and ways to manage their money, as well as allowing access to new products and services that were simply not previously available to them before.

    • The author, Karen Nadasen, is CEO of PayU South Africa

    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    Karen Nadasen PayU Reserve Bank Sars South African Reserve Bank
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleMTN quits talks to buy Telkom
    Next Article Alleged thieves nabbed at Eskom power stations

    Related Posts

    South Africa's digital ID is here - but you can't have it yet - Leon Schreiber

    South Africa’s digital ID is here – but you can’t have it yet

    1 October 2026
    Major bank joins crypto fight against Reserve Bank draft rules

    Major bank joins fight against draft crypto rules

    28 September 2026
    Insurers carry the can for MIP breach, regulators say

    Insurers carry the can for MIP breach, regulators say

    25 September 2026
    Company News
    Cloud and AI won't deliver value on their own, executives warn

    Cloud and AI won’t deliver value on their own, executives warn

    1 October 2026
    Dell Technologies Forum 2026: what to expect in Johannesburg

    Dell Technologies Forum 2026: what to expect in Johannesburg

    1 October 2026
    What Smollan learnt moving 9 000 users to Google Workspace - Digicloud Africa

    What Smollan learnt moving 9 000 users to Google Workspace

    1 October 2026
    Opinion
    South Africa's next energy crisis is in the accounts department - Craig Holmes

    South Africa’s next energy crisis is in the accounts department

    29 September 2026
    The steam engine lesson AI doomsayers keep missing - Sam Clarke

    The steam engine lesson AI doomsayers keep missing

    28 September 2026
    Regulating AI: apply the laws we have first - Dirk de Vos

    Regulating AI: apply the laws we have first

    21 September 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    Usaasa consults on universal access as its abolition stalls

    Usaasa consults on universal access as its abolition stalls

    2 October 2026
    Frogfoot plots acquisitions as Octotel and MetroFibre weigh a merger - Shane Chorley

    Frogfoot plots acquisitions as Octotel and MetroFibre weigh a merger

    2 October 2026
    Home affairs pulls the plug on the green ID book - Leon Schreiber

    Home affairs pulls the plug on the green ID book

    1 October 2026
    South Africa's digital ID is here - but you can't have it yet - Leon Schreiber

    South Africa’s digital ID is here – but you can’t have it yet

    1 October 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter