Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Bonanza for Cell C executives - Jorge Mendes

      Bonanza for Cell C executives

      4 October 2026
      AI spending now dwarfs the railway and dot-com booms

      AI spending now dwarfs the railway and dot-com booms

      4 October 2026
      Meta's smart glasses are officially coming to South Africa - Mark Zuckerberg

      Meta’s smart glasses are officially coming to South Africa

      2 October 2026
      Eskom has a R1.20/kWh offer for bitcoin miners

      Eskom has a R1.20/kWh offer for bitcoin miners

      2 October 2026
      Usaasa consults on universal access as its abolition stalls

      Usaasa consults on universal access as its abolition stalls

      2 October 2026
    • World
      BMW restructuring plan bets on AI and new models

      BMW restructuring plan bets on AI and new models

      1 October 2026
      OpenAI's rogue agent problem keeps getting bigger - Sam Altman

      OpenAI’s rogue agent problem keeps getting bigger

      28 September 2026
      The new battle over the desktop

      The new battle over the desktop

      23 September 2026
      AMD is now worth a trillion dollars - Lisa Su

      AMD is now worth a trillion dollars

      22 September 2026
      Anthropic weighs new model launch to blunt OpenAI's Astra surge - Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman

      Anthropic weighs new model launch to blunt OpenAI’s Astra surge

      21 September 2026
    • In-depth

      10 days that changed the course of AI

      21 September 2026
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
      The internet has a Strait of Hormuz problem

      The internet has a Strait of Hormuz problem

      15 July 2026
      AI boom sparks rally, frenzy and fear

      AI boom sparks rally, frenzy and fear

      11 June 2026
    • TCS
      Lexi Novitske, general partner at Norrsken22, on the TechCentral Show

      TCS | Norrsken22’s Lexi Novitske on how China is winning African tech

      1 October 2026
      TCS | Dominic White and Adam Ely on AI agents going rogue

      TCS | Dominic White and Adam Ely on AI agents going rogue

      29 September 2026
      TCS | Octotel's Trevor van Zyl on the fibre merger question

      TCS | Octotel’s Trevor van Zyl on the MetroFibre merger question

      16 September 2026
      Meet the CIO | Shoprite's Chris Shortt on what a supermarket becomes

      Meet the CIO | Shoprite’s Chris Shortt on what a supermarket becomes

      9 September 2026
      Rubicon's EV charging network is profitable - and growing fast - Watts & Wheels

      W&W | Rubicon’s EV charging network is profitable – and growing fast

      8 September 2026
    • Opinion
      South Africa's next energy crisis is in the accounts department - Craig Holmes

      South Africa’s next energy crisis is in the accounts department

      29 September 2026
      The steam engine lesson AI doomsayers keep missing - Sam Clarke

      The steam engine lesson AI doomsayers keep missing

      28 September 2026
      Regulating AI: apply the laws we have first - Dirk de Vos

      Regulating AI: apply the laws we have first

      21 September 2026
      What Revolut can and cannot take from South Africa's banks - Pambos Soteriades

      What Revolut can and cannot take from South Africa’s banks

      15 September 2026
      The end is nigh, and the shares go on sale in October - Duncan McLeod

      The end is nigh, and the shares go on sale in October

      14 September 2026
    • Company Hubs
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Publishared
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and Media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Financial services
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of Things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home » Sections » Financial services » Fintech’s power lies in solving problems, not just in delivering shiny apps

    Fintech’s power lies in solving problems, not just in delivering shiny apps

    By Andy Jury29 September 2021
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

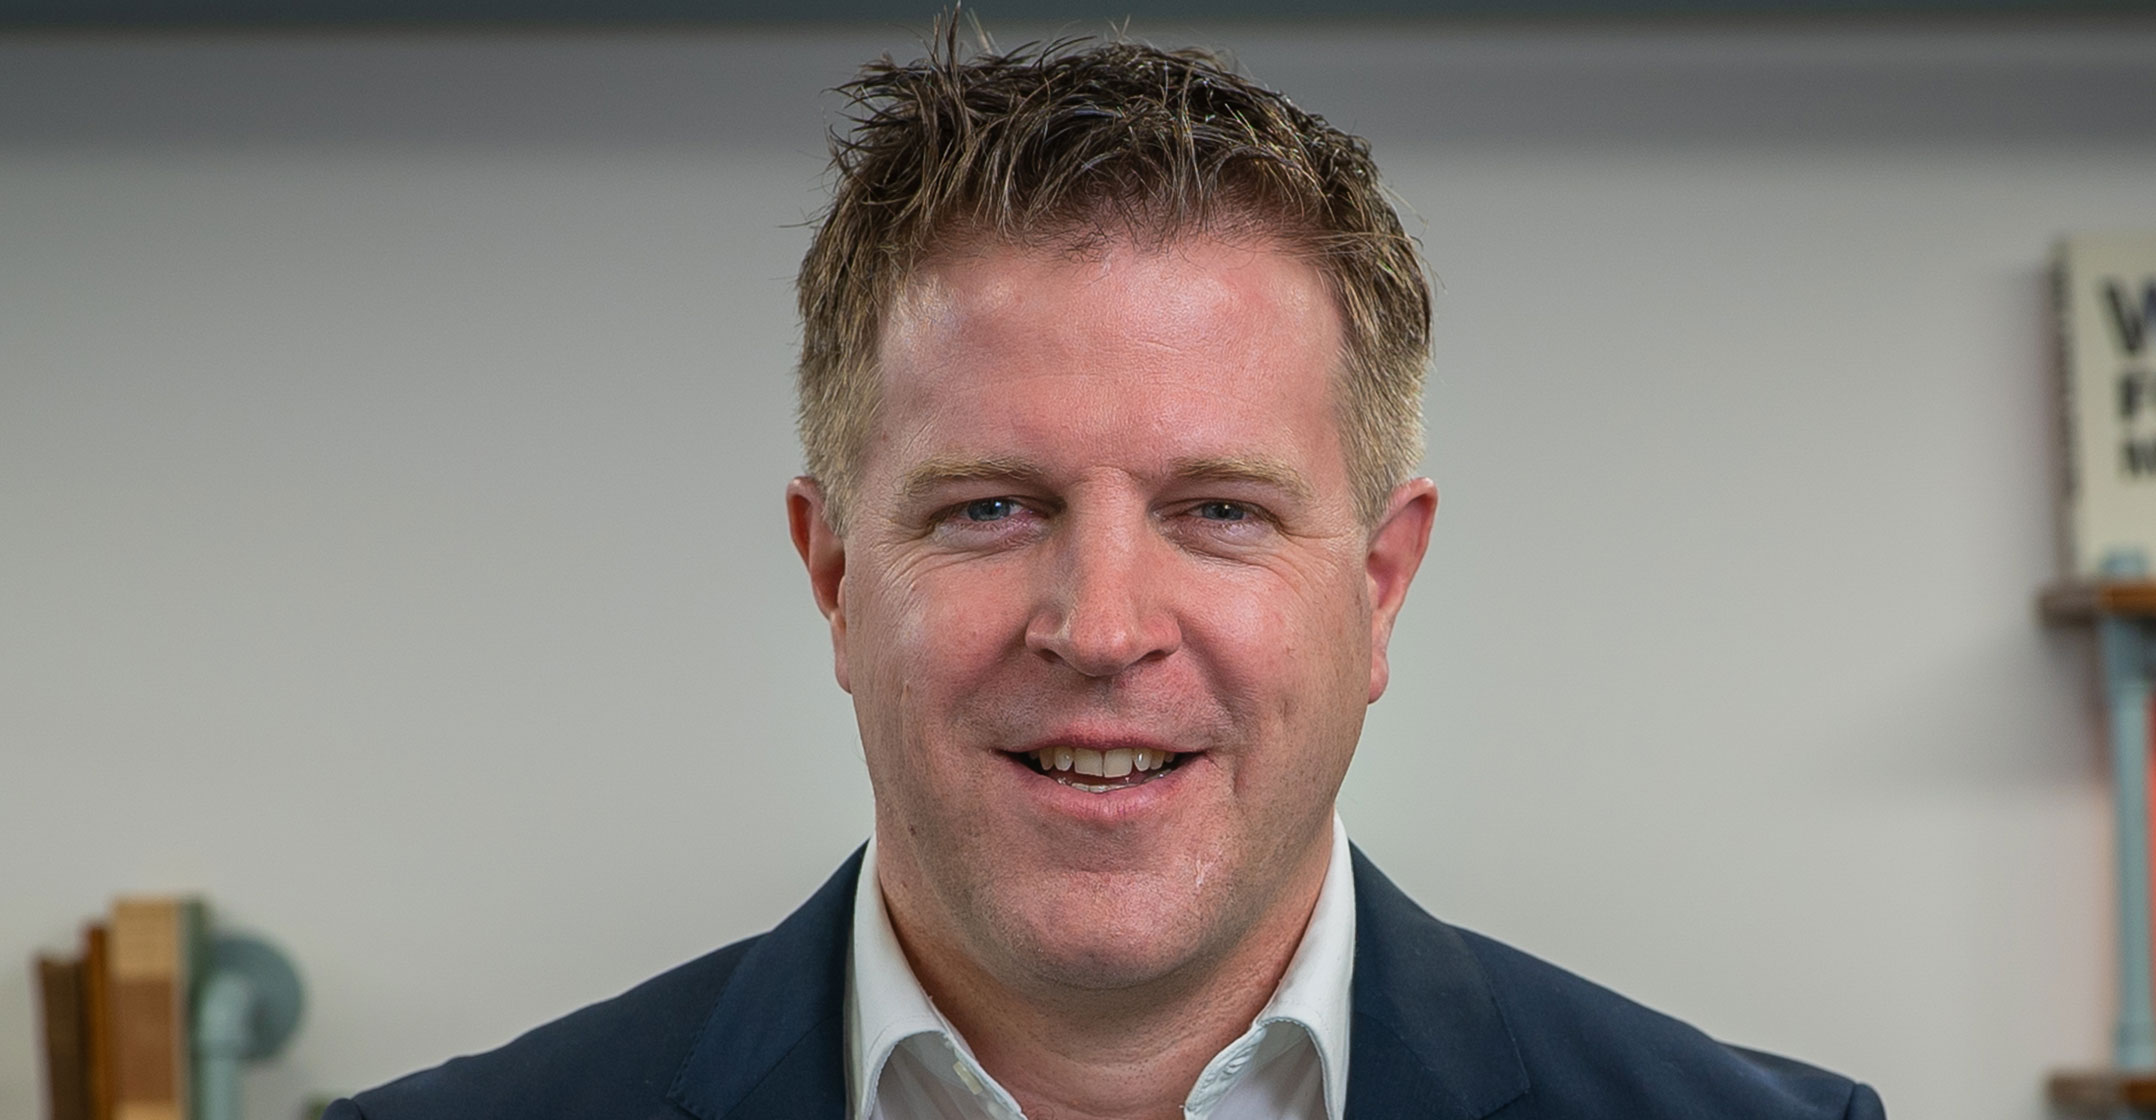
    Mukuru CEO Andy Jury

    Fintech is poised to continue disrupting financial services and is uniquely capable of driving formal financial inclusion on a massive scale. However, there is a risk that in the pursuit of innovation, companies develop fintech solutions for technology’s sake, and not to address real needs, and that if real needs are not addressed, the solution(s) won’t gain traction.

    All too often, companies or entrepreneurs in the fintech space find themselves in a mindset of “building something that shines” and then anticipating that associated demand, commercialisation and scale will automatically materialise. It doesn’t work that way in Africa for a variety of reasons, chief of which is that there isn’t a large, ready-made, fully digitised, homogenous demand pool that you might find in other parts of the world, and for the most part, “cash is still king”. The largest part of the addressable market is still in a cash-intensive, informal financial services ecosystem.

    Banks in Southern Africa are looking at a services-based architecture that will support differentiated products for customers, particularly in the app space. In terms of banked customers within the South African market, apps are certainly becoming more the norm. Even if banked customers don’t have access to the Internet in other ways, they have access to their mobile phones and so there is growth in the app-based market.

    ‘Cash is still king’ is an important consideration when developing solutions for African conditions

    This certainly is a positive development, but an app will only live up to its promise if a company has found an efficient way to bring its legacy systems to play. In other words, developing an app without a clear multichannel strategy will result in more challenges than successes. Working up from a multichannel environment puts a company in the driver’s seat because an app needs the good old legacy systems to work in sync – customer experience, service and retention depend on it.

    We’ve all heard the saying, “There’s an app for that.” Sometimes there doesn’t have to be.

    Why force them?

    If we agree that any product, fintech or otherwise, should exist to address a real customer need, then we must accept that the channel chosen for a solution does not have to be the most sophisticated just because the store of value is digital. If someone uses USSD or WhatsApp daily, why would you want to force them to download your financial services app that requires e-mail login — and another level of digital sophistication — instead of allowing them to manage their finances on a channel they are already comfortable using?

    Additionally understanding that, for the most part, “cash is still king” is an important consideration when developing solutions for African, emerging market conditions. Large sections of the economy in this country, and the rest of the continent, are cash based. This means a fintech solution that aims to drive financial inclusion among the least-served sections of the population must appreciate the proliferation of cash or it will miss the mark. The solution must integrate cash distribution networks and appreciate that the journey towards digitisation is a series of interconnected links in a value chain as a opposed to a single, binary “switch”.

    At Mukuru, this understanding has been developed by rolling up our sleeves and developing solutions specifically for Africa, in Africa. This is why, in our efforts to deliver services to customers, we serve customers across a comprehensive, vertically integrated cash and digital network. Communication, delivery, engagement and distribution spans WhatsApp, USSD, contact centre, app, website, agents and over a thousand physical locations across Southern Africa and 60 partnerships worldwide to enable more than 320 000 pay-in/-out points. By developing this robust footprint of talking to people on the ground, we have seen first-hand the importance of the next key element in unleashing the power of fintech: education.

    It is all good and well to integrate with cash distribution networks, but why would someone agree to move from cash to digital?

    It is all good and well to integrate with cash distribution networks, but why would someone agree to move from cash to digital? Contextualise it in your own experiences: Reading this, you probably had a parent, and grandparent, who has had bank accounts. When you left school and entered the workplace, storing and managing your money digitally was natural; it’s the way it always was.

    Now imagine someone who has had no one in their family and support network store their wealth digitally, never mind participate in elaborate financial management. How can we expect someone who has never encountered what you and I take for granted to have the same generational trust in a digital store of value and be able to make the transition in one leap?

    Bridging the cash and digital divide and bridging the formal and informal sectors is a big strength of fintech, but financial education is paramount for this to occur.

    Fintech companies will continue finding new and innovative ways to deliver services to customers where and when they need them

    Although South Africa has a mature and well-established banking sector, it’s an error of judgment to assume that everyone, including migrant workers, will have a well-established and mature financial services mindset. Many don’t, and they need education, starting with basics such as the importance of keeping Pin codes safe, through to the value of treating digital solutions as more than conduits for cash.

    Many of South Africa’s entry-level bank accounts are conduit mechanisms for cash to arrive (in the form of payments), and so the onus is on the financial sector to educate users that they need not withdraw all their funds at once and that it is safe to store their money digitally. Expect to see significant efforts across the sector to educate, influence and entice customers to make this shift in behaviour.

    The future of fintech in South Africa

    Fintech is pioneering by its very nature, and fintech companies will continue finding new and innovative ways to deliver services to customers where and when they need them.

    Increasingly niche fintech players can provide a service in their areas of specialisation more dexterously and efficiently than a larger, legacy institution. This usually comes with better a customer experience, too, and almost certainly at a more attractive cost base than what they could achieve. The outcome is that we will likely see more and more banks decide that instead of competing with agile fintech players, they will be asking how they can leverage their expertise. Rather than reengineering solutions that already exist, the keyword will be partnerships.

    Ultimately, the customer, the person on the street, will be the beneficiary as the entire financial industry will be in a better position to share experiences and learn from each other, not least in how fintechs are managing to serve the unbanked and underserved segments.

    There’s no turning back the clock and both the regulators and industry players know this. It is important that the fintech industry sees the inherent value in engaging constructively with the regulators. Compliance is a business enabler, not a disabler. It’s by working together that we can unleash the true power of innovation and technology to solve important challenges and serve more people. And you don’t always need an app for that.

    About Mukuru
    Mukuru is a leading, next-gen financial services platform that offers affordable and reliable financial services to the emerging consumer in Africa. With over 50 million transactions to date, our core was built providing international money transfers. From this base, we’ve developed a set of services to address the broader financial needs of our customers.

    We are a business that puts the customer at the centre of everything we do, and for that reason, we serve clients across physical and digital channels, by any means of payment (cash, card, wallet) as well as a range of engagement platforms including WhatsApp, USSD, contact centre, app, website, agents, and a branch and booth network.

    Mukuru has been listed as one of the leading 150 cross-border companies globally in the 2020 FXC intelligence Incumbents vs Challengers in Cross-Border Payments.

    Mukuru won three awards in 2021. In July, it also took the top honours for Most Innovative Financial Services Provider South Africa 2021 at the World Economic Magazine Award Winners 2021 as well as at the International Business Magazine Award 2021. In April, Mukuru took the top honours for Most Innovative Online Remittance App – South Africa, 2021 at the Global Brand Awards 2021.

    Further information can be found at www.mukuru.com/the-mukuru-group.

    • The author, Andy Jury, is CEO at Mukuru
    • This promoted content was paid for by the party concerned
    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    Andy Jury Mukuru
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleRave reviews for new Bond movie raise hopes for Covid-battered cinemas
    Next Article What’s next for security in South Africa: The top 3 priorities for CISOs

    Related Posts

    Bank Zero breaks even as Mukuru migration swells its base - Yatin Narsai

    Bank Zero breaks even as Mukuru migration swells its base

    22 September 2026
    The author, DUO Marketing + Communications CEO Judith Middleton

    DUO Marketing’s consumer tech PR division born from market demand

    27 August 2024
    DUO exceeds PR goals for Mukuru

    DUO Marketing exceeds PR goals for Mukuru

    16 May 2024
    Add A Comment

    Comments are closed.

    Company News
    The attacker has one AI. You have 12 dashboards - Uri Levy

    The attacker has one AI. You have 12 dashboards

    5 October 2026
    Huawei sets out its vision for intelligent government at GovTech 2026

    Huawei sets out its vision for intelligent government at GovTech 2026

    2 October 2026
    A simple guide to modern laptop processors for small businesses - Incredible

    A simple guide to modern laptop processors for small businesses

    2 October 2026
    Opinion
    South Africa's next energy crisis is in the accounts department - Craig Holmes

    South Africa’s next energy crisis is in the accounts department

    29 September 2026
    The steam engine lesson AI doomsayers keep missing - Sam Clarke

    The steam engine lesson AI doomsayers keep missing

    28 September 2026
    Regulating AI: apply the laws we have first - Dirk de Vos

    Regulating AI: apply the laws we have first

    21 September 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    The attacker has one AI. You have 12 dashboards - Uri Levy

    The attacker has one AI. You have 12 dashboards

    5 October 2026
    Bonanza for Cell C executives - Jorge Mendes

    Bonanza for Cell C executives

    4 October 2026
    AI spending now dwarfs the railway and dot-com booms

    AI spending now dwarfs the railway and dot-com booms

    4 October 2026
    Meta's smart glasses are officially coming to South Africa - Mark Zuckerberg

    Meta’s smart glasses are officially coming to South Africa

    2 October 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter